

The Architecture of Financial Stewardship: A Blueprint for Calibrated Asset Management
The Vickerson Philosophy is an institutional framework for private capital stewardship, moving beyond reactive asset management. By utilizing five core pillars—the Capital Shield, active portfolio drift monitoring, adaptive life-stage allocation, a tri-annual communication cadence, and data-driven analytical tools—it provides high-net-worth households with an engineered, predictive approach to long-term wealth preservation and multi-professional coordination.
Engineered anticipation replaces reactive management.
When private capital accumulates, a household faces a permanent shift from the mechanics of asset accumulation to the deeper complexities of long-term preservation. For affluent families and those navigating retirement, this complexity often introduces a single, critical question: Is every moving part of my financial ecosystem properly aligned, or is there an unmapped risk developing beneath the surface?
In traditional environments, capital oversight operates reactively. Advisors wait for the client to flag a concern, request a transaction, or manage the administrative friction between separate accounting and legal professionals.
Our practice operates on an entirely different standard: The Vickerson Philosophy. We believe that the highest form of respect and care for your lifetime of capital is a system governed by engineered anticipation.
In Japanese culture, this hyper-prescient standard of care is known as Omotenashi—the practice of completely understanding and preparing for a client’s operational needs before they ever have to ask.
We do not rely on ad-hoc adjustments. We rely on institutional governance. This framework outlines the definitive structure of our practice. Every strategic decision we make, and every real-world case study we publish, maps directly back to these five operational pillars.
1. The Capital Shield: The First Step of the Engineered Portfolio
Risk mitigation across a large balance sheet can be approached through different, methodologies. A common and recognized practice is to diversify capital across multiple separate investment management teams. While this style provides an institutional spread of professionals, it introduces a specific vulnerability: underlying position overlap. When independent management firms buy from the same universe of high-capitalization global equities, the portfolio often duplicates holdings beneath the surface. This creates an unmapped concentration in a single asset or sector, exposing a household to uncalibrated risk.
Our practice utilizes a different architecture. While also utilizing different management teams, we build an Engineered Portfolio that adds an additional layer of risk management where diversification is precisely mapped across asset classes, capital structures, geographic footprints, and macro allocations.
The structural foundation for this approach is The Capital Shield, which serves as the absolute first step in building a resilient financial plan. We isolate top-tier management teams and confine them strictly to specific, non-overlapping operational sleeves.

The Capital Shield segments capital into three distinct asset sleeves to ensure that every holding has a singular, engineered purpose:
-
1
The Growth Engine: High-quality, broadly diversified equity assets deployed globally to maintain purchasing power and drive long-term compounding.
-
2
The Income/Debt Fuel: A structurally ring-fenced sleeve combining low-volatility fixed-income assets, Canadian dividend-producing equities, and alternative income sources from liquid alternatives. This structure is mathematically engineered to insulate and generate stable, predictable cash flow through any macroeconomic regime.
-
3
The Wildcat Accelerator: Dedicated opportunistic capital positioned to capture value during severe market dislocations or specialized alternative events.
Where other frameworks stop at diversifying management teams, our system adds this mandatory layer of structural allocation. By mapping each top-level manager to a specific, ring-fenced sleeve, we separate out and eliminate asset duplication. No single position can be accidentally overweighted. This advanced level of application and care ensures that diversification functions as an active system of risk management. The architecture is deliberate.
2. Preventing Portfolio Drift: Monitoring the Capital Shield
Once the Capital Shield is established, its performance and structural baseline are continuously audited. Left entirely unmonitored, market movements will slowly alter the proportions of your assets over time, leading to Portfolio Drift.
Preventing drift requires rigorous, continuous monitoring of the Capital Shield, but our execution method rejects the standard industry practice of automated, programmatic rebalancing. Automated systems trigger transactions blindly based on rigid mathematical thresholds. This automated execution frequently forces the premature liquidation of outperforming assets, cutting off growth momentum and sacrificing opportunity.
Our rebalancing approach is strictly tactical and intentional. If prevailing market conditions validate an outperforming position—and a clear forward path exists for continued capital growth—we intentionally allow the allocation to run. We do not place arbitrary limits on net progress simply to satisfy a generic software rule. Rebalancing inside our framework is an active, analytical decision designed to insulate capital from unmapped risk without truncating your growth path.
3. Strategic Allocation: Adapting to Shifting Life Stages
While the core institutional building blocks of our engineered portfolio remain exceptionally robust, the allocations inside the system are never static. True alignment means recognizing that while two households might hold identical underlying institutional asset classes, their specific weightings must look completely different based on their immediate season of life.
Inside the engineered portfolio, we dynamically adjust asset weights via our Adaptive Allocation Framework to track your household lifecycle milestones:
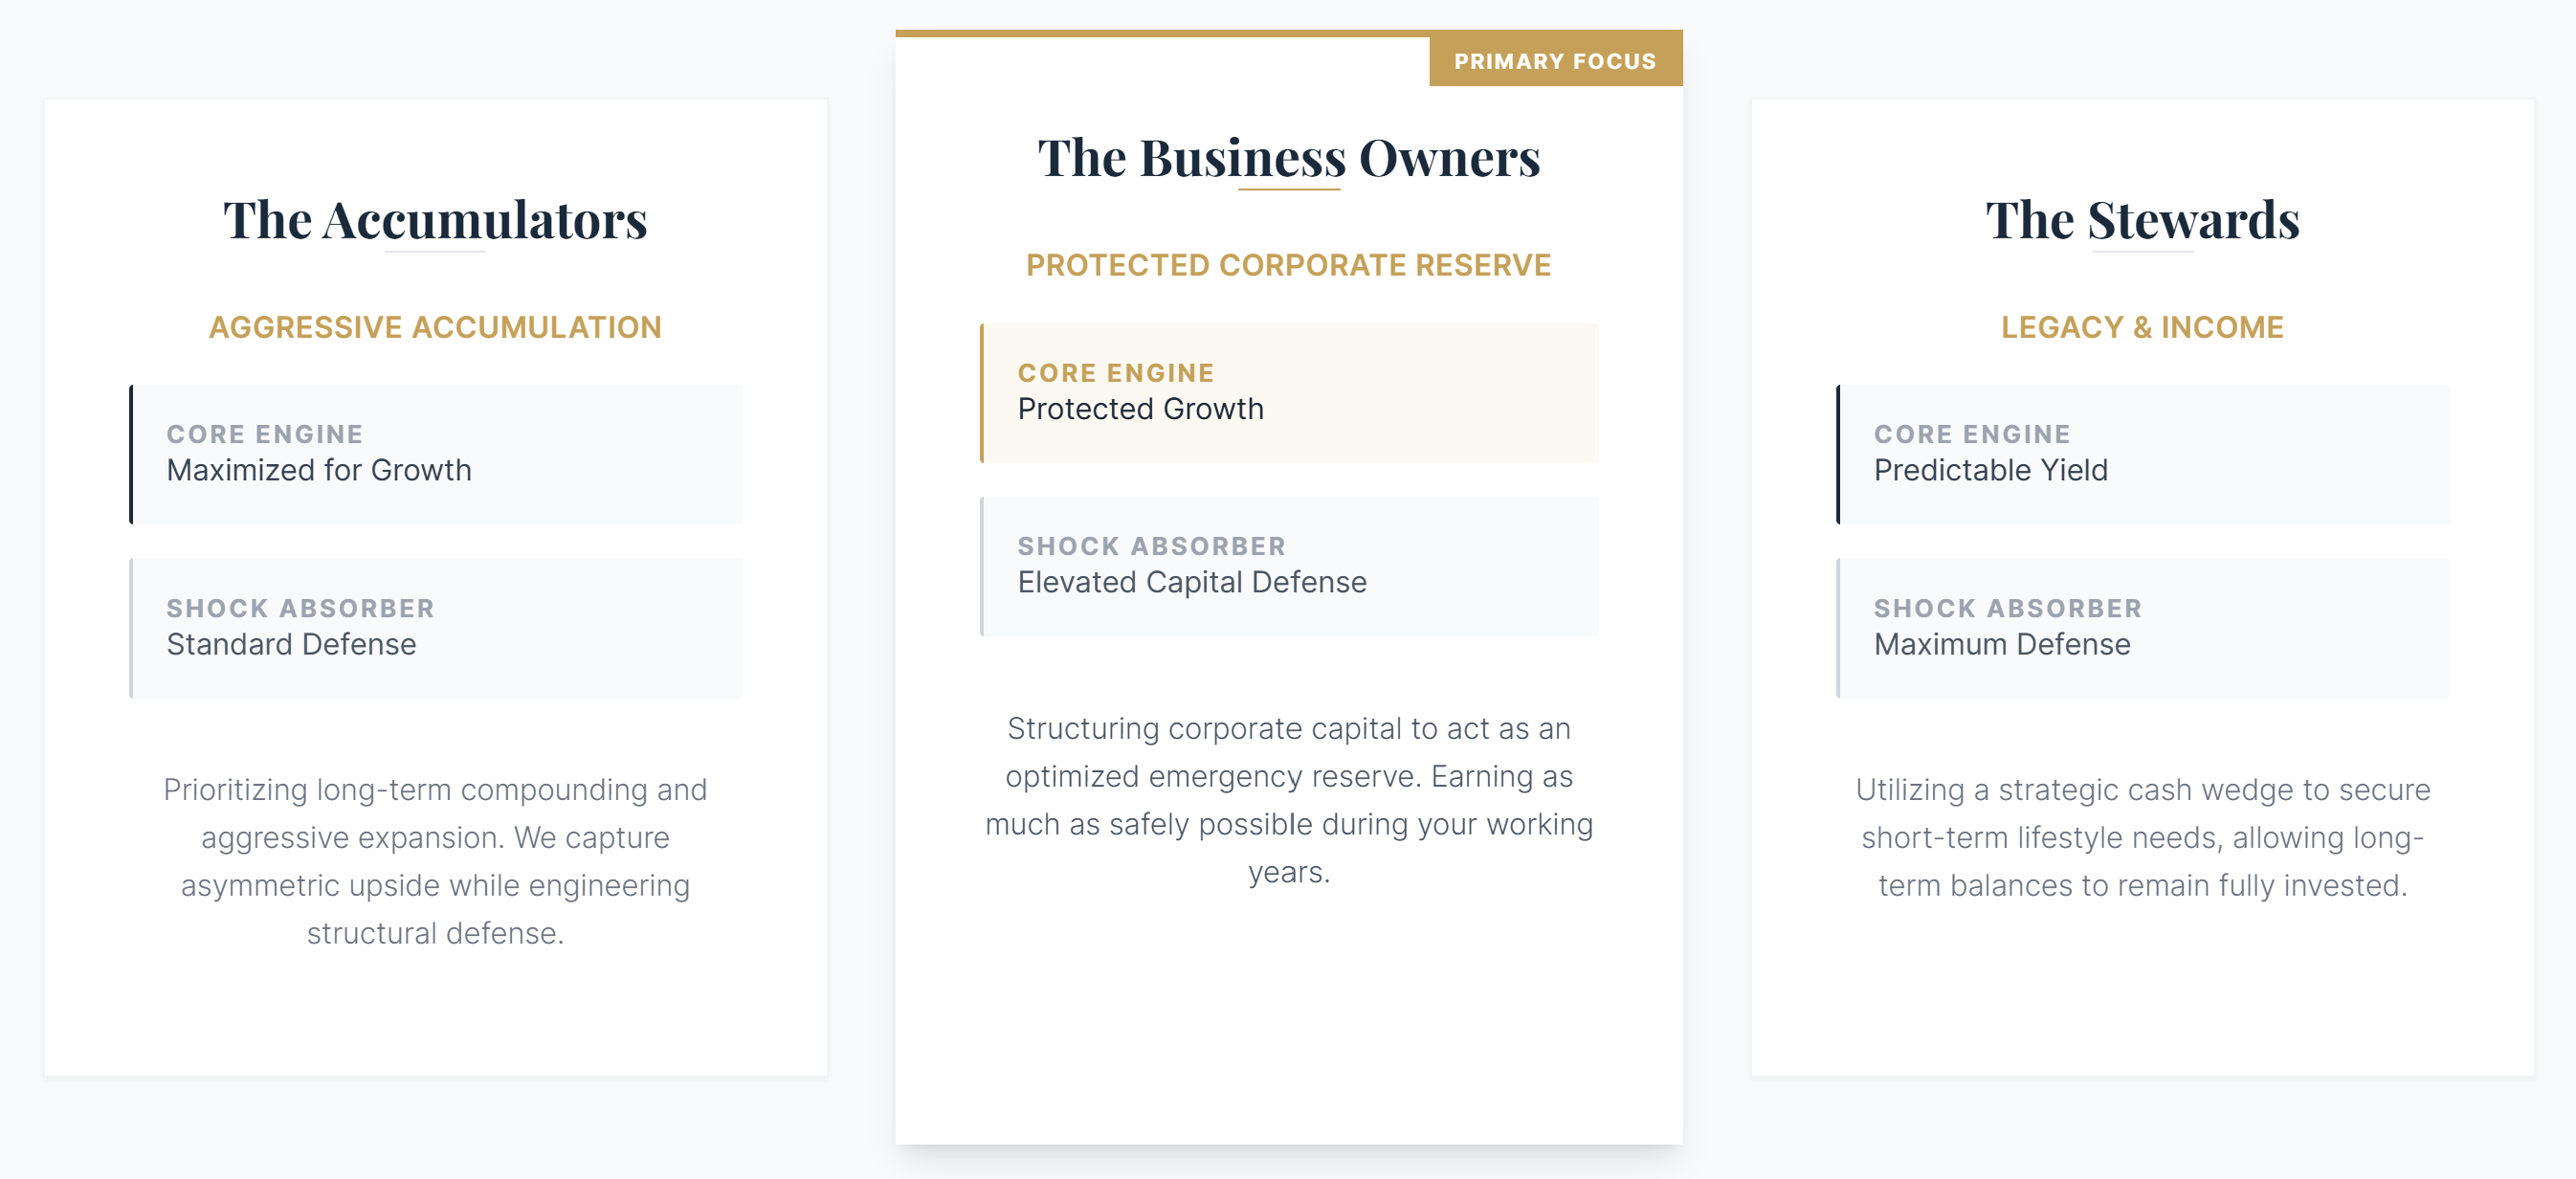
Accumulators & Mid-Career Professionals
Maximizing the Growth Engine to leverage long compounding horizons while establishing basic liquidity guardrails.
Corporate Liquidity & Business Owners
Isolating corporate cash flows, managing retained earnings tax-efficiently, and decoupling personal capital from operational business liabilities.
Stewards & Retirees
(Ages 55–70)
Shifting weightings decisively toward Income Fuel, establishing ironclad withdrawal sequencing, and optimizing the structural handoff of assets.
By continuously shifting these weightings to match your life stage, your capital always directly serves your current real-world obligations.
4. The Tri-Annual Cadence: Systematic Execution of the Comprehensive Plan
The first three pillars of our philosophy outline how we invest. This pillar defines how we execute.
Properly managing a household's complete financial family life involves an immense volume of moving structural pieces. In traditional frameworks, communication is aimless, sporadic, or purely reactive—a breakdown that exposes families to unmapped administrative oversights. Attempting to address tax compliance, estate mitigation, corporate structures, and liquidity needs in a single, massive annual meeting inevitably creates cognitive overload.
To deliver a true multi-family office standard of care, we break this workflow into the Tri-Annual Cadence. This structural timeline splits the operational year into three highly disciplined seasonal windows.
This division makes our execution entirely systematic, repeatable, and thorough. By spreading the workflow across three distinct contact points, we prevent any single meeting from becoming overwhelming. It allows us to continuously verify that the system is running correctly, proactively anticipate upcoming transitions in your family life, and catch critical structural trends early. Absolutely nothing is left to chance.

All deep macro-research, tax modeling, and cross-professional checking are completed internally before a review window opens. This proactive rhythm allows you to execute your Chief Financial Officer Mandate.
We act as the central coordinator for your household, communicating directly with your Accountant and Lawyer behind the scenes. This ensures your professional silos are fully aligned, saving your family administrative time and ensuring technical precision.
5. The Instruments of Certainty: Data-Driven Decision Tools
Excellence is the byproduct of a rigorous system, not an accident of human sweat. To remove guesswork entirely from long-term capital preservation, our framework utilizes a specific suite of analytical tools and inputs to turn raw data into clear, operational choices.
These resources govern our tri-annual decision-making process:
- Financial Planning Software: We use a central CRM and advanced planning software updated specifically to meet Financial Planning Canada standards. This builds the foundational mathematical baseline for all of your long-term projections.
- Portfolio Creation Tools: We use specialized design tools to track underlying holdings for unexpected risk and overlap. This lets us monitor exactly what independent management teams hold, ensuring you don't accidentally replicate identical equity concentrations across different funds.
- Income Projection Spreadsheets: Long-term cash flow sustainability and withdrawal sequencing are stress-tested through custom spreadsheets built specifically for income projections. These let us model multi-decade longevity runways through changing market environments.
- Advanced Technology & AI Processing: We incorporate advanced AI tools to increase our operational speed and accuracy with heavy data tracking. However, my view on technology is clear: it is only there for the heavy processing and data lifting. Human interaction starts the conversation, and a human professional ends it.
- Professional Coordination: A plan is only as accurate as the facts behind it. We work directly with your corporate accountant and estate lawyer to ensure your tax returns, corporate flowcharts, and legal documents are correctly reflected in the strategy. Cross-verifying these pieces ensures everything we do is properly informed by the other areas of your financial family life.
Following the Thought Process: The Launchpad for Case Studies
This master architecture serves as the baseline blueprint for everything we do. Moving forward, we will use this website to regularly publish technical Case Studies demonstrating how these specific pillars resolve real-world complexity. By walking through these structural, corporate, and multi-professional scenarios, you will be able to follow our analytical process—seeing exactly how capital is positioned and why specific adjustments are made to maintain long-term stability.
The Vickerson Standard
By merging the unyielding logic of institutional investment infrastructure with a quiet, anticipatory model of care, we replace speculation with systematic governance. This is how private capital is protected.


2 responses to “The Vickerson Philosophy: My Foundational Framework”
[…] Follow these links to see my Operating Method and Decision Making Framework . […]
[…] cover lifestyle needs between ages 61 and 70, they executed an RRSP/RRIF meltdown governed by The Tri-Annual Cadence (Winter, Spring, Fall tax position audits) to fill their lowest personal marginal brackets without […]